

TL;DR
Bitcoin price is at the 24th percentile level, up from p18 at our September check-in headline.
RIS remains decisively below the sample p90 threshold, while TS sits well inside a normal range.
2Y β remains the holdout: despite normalization elsewhere, the rolling exponent has continued moving away from baseline.
In Foundations Check-In: September 2026, we tracked RIS, RIS percentile, and Transition Score through the release of the longest p90+ streak of this cycle. We asked when RIS would stay below p90, whether price percentile would keep recovering, and whether the 2Y exponent would reverse after RIS and TS normalized. We also flagged a possible repair ordering: instability scores normalize first, with rolling β following.
One month later, the first two questions have largely resolved. The third, 2Y exponent repair, remains open.
Let’s get an update on how those readings have evolved since September, and what they imply for the conditions we described last month.
Novara Research now publishes Bitcoin Research data. Get started today!
October 3, 2026 @ $85,896 (p24.3)
Research as of: 10/03/26
Bitcoin remains ~42% discounted relative to its implied path (~$147,267). Seven months have now passed since we initially wrote about this price regime (Don’t be surprised this year). Price has held above $81k since early September, but the discount zone is still deep by historical standards.
Daily Drift Diagnostics (2026-10-03)
Exponent: 5.5728 (−1.366%): trend below our central anchor.
R²: 0.9437 (+0.0848%): strengthening above our model baseline.


Despite an ongoing trend below the central power-law attractor, Bitcoin’s scaling relationship remains intact (structural integrity).
Regime progress table (October update)
Introduced in our June check-in and updated periodically, let’s check in on the latest:
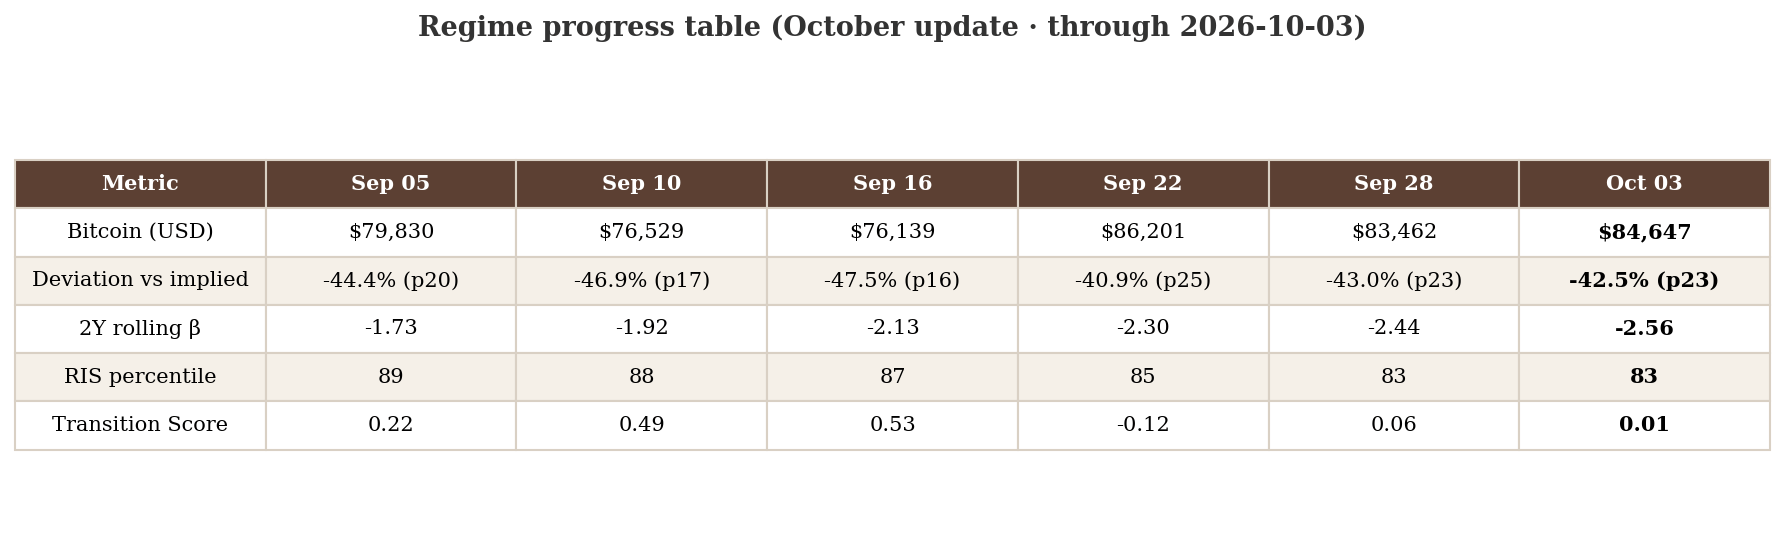
September was a choppy recovery: a mid-month dip toward $76k, a Sep 22 push near $86k, then a low-$83k–$86k band into October. Deviation percentile ran from p20.5 (Sep 5) to p16.0 (Sep 16) and back to p23.2 at the time of our research cutoff.
RIS and TS are normalizing from summer highs:
RIS percentile: 89 → 83 (Sep 5–Oct 3). Returning from the summer spike, with no signs of re-entry above p90.
Transition Score: sub-threshold all month (high 0.56; Oct 3 0.01).
2Y β has not yet followed: −1.73 → −2.56. The trailing fit still reads stressed until β turns.
RIS: four weeks below p90
In September we reported the 63-session p90+ streak ending with two consecutive sub-p90 levels. We cautioned that RIS can chop around the threshold during volatile repairs.
So far, it has not shown signs of chopping back above.
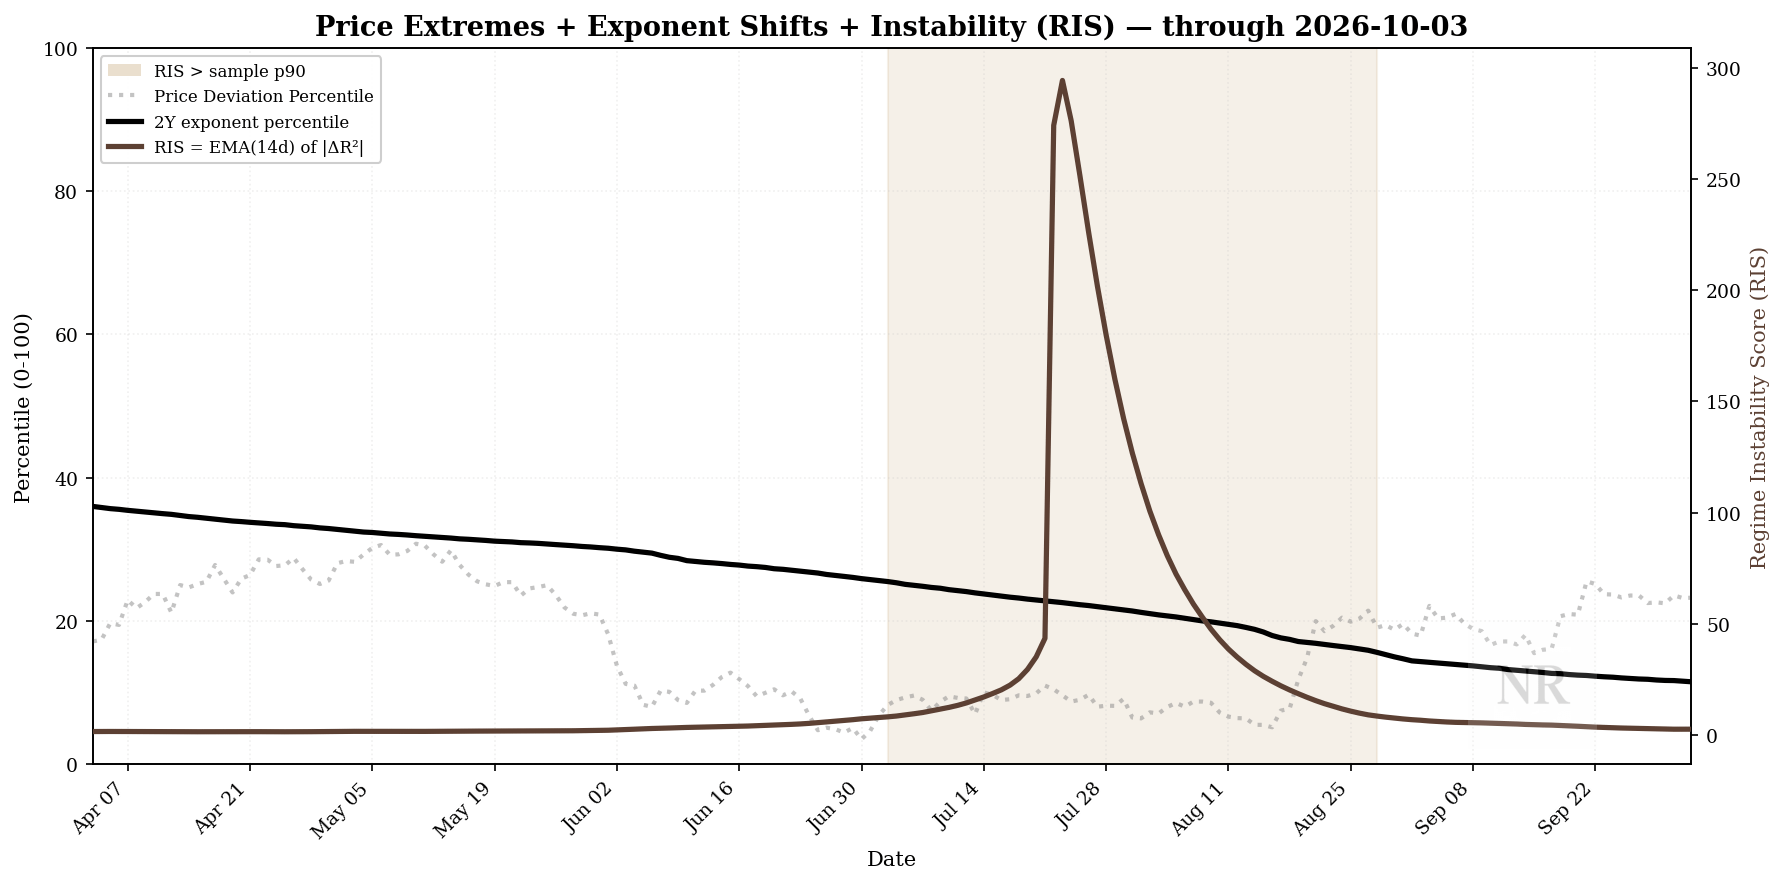
Since our last report:
RIS percentile registered 33 consecutive sessions below p90.
RIS today reads 2.59 (p82.6), down from 6.6 (p89.6).
In the chart above, the tan-shaded p90 zone is now clearly behind us. The instability leg that opened in late June has unwound and remained contained. With that release, the data increasingly resembles the quiet valley we’ve been watching for.
Prior cycles have shown RIS can re-accelerate if 2Y fit stress returns. However, we’re not seeing those conditions in this data.
Transition Score: still normalized after July
September left TS at 0.40, far from the 9.61 July 22 peak. The follow-up was whether sub-threshold readings would persist or re-accelerate into the historical top 5%.
They persisted and softened even further.
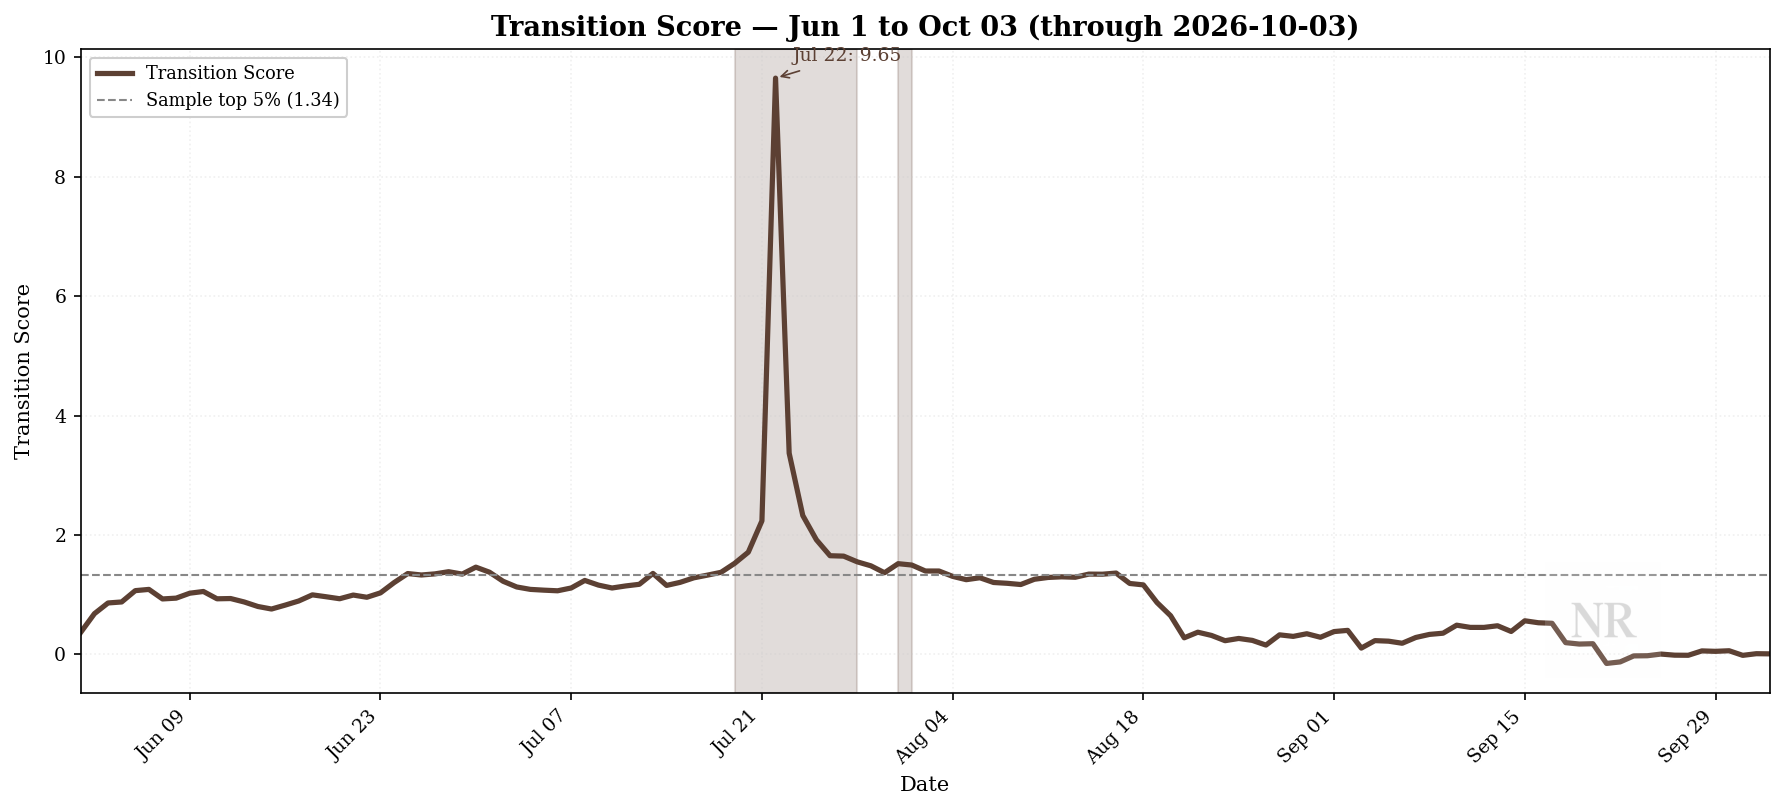
September: TS peaked at 0.56 (Sep 15); far from the sample top 5%.
Latest: TS reads 0.01, firmly back in the low-stress regime and far removed from July’s extremes.
The July 19 through August 1 window that registered 12 sessions in the top 5% range still looks like the cycle maximum for Transition Score so far. September’s outlook item, “Does TS re-enter the top 5%?”, has been a no for two consecutive check-ins. That remains consistent with the quiet-valley regime we’ve been tracking.
2Y exponent: repair still pending
Our September report left one item unresolved: How long it would take the 2Y exponent to turn around and establish a positive trend. At our latest research cutoff, the trend is still down.
Since last report:
2Y β: −1.63 → −2.56. The rolling level moved further from baseline, not toward repair.
The “dance” between RIS, the 2Y rolling window, and price deviation plays out below, and the summer story comes into context across a backdrop of cyclical stress events.
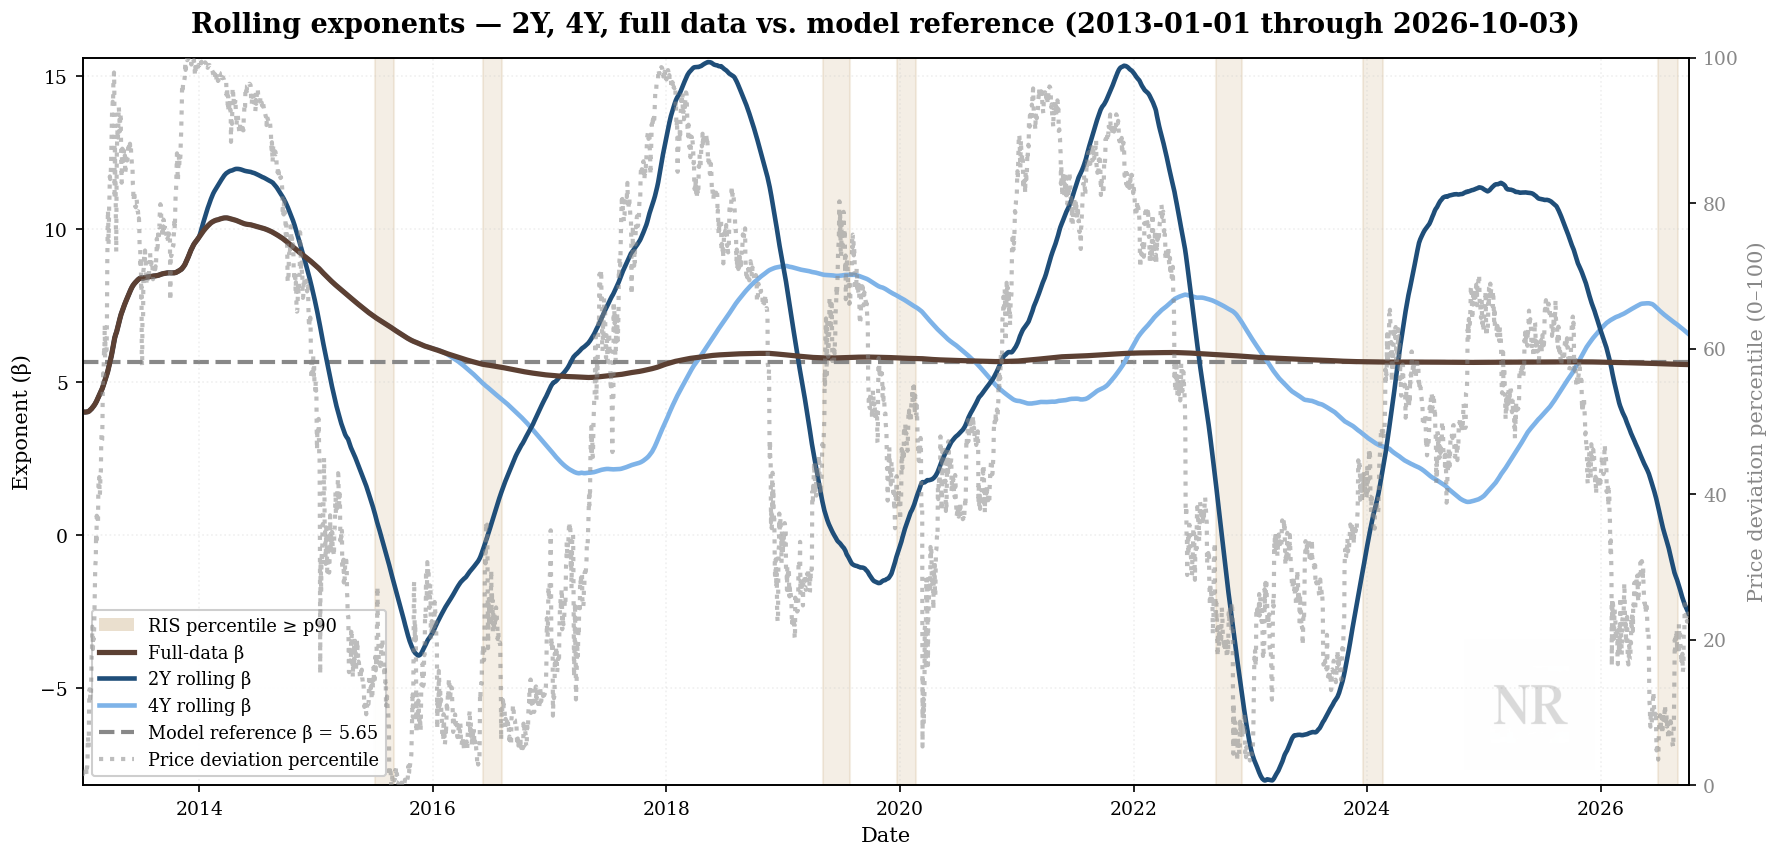
Simply put: Deviation percentile on the right has been grinding up from midsummer lows, but the 2Y level has not followed that repair yet.
That remains the defining split in October: RIS and TS have normalized, while 2Y β continues to deteriorate.
4Y β (light blue; 6.57) rides on the same panel and has stayed much nearer the model reference while 2Y β broke down (background context we have noted in earlier check-ins.) We will say more about the longer window once 2Y β confirms a corrected trend.
Outlook
Things we’re looking out for:
Does RIS remain comfortably below p90, confirming the summer instability regime is behind us?
Does price percentile continue grinding higher while TS remains subdued?
Most importantly, when does 2Y β finally turn? With RIS and TS already normalized, that remains the missing piece in the repair sequence.
Conviction and Patience
Watch the structure and don’t be surprised. Keep on top of our latest research and support our work.
Don’t forget, now YOU can monitor the structure, using real Novara Research data!
Research infrastructure, not financial advice.
Foundations of Conviction
Foundations Check-In: September 2026
Foundations Check-In: August 2026